
DCP Capital signs US$2.0bn deal for sausage maker Jinluo
DCP Capital has signed documents to buy Shandong meat processor Jinluo for about US$2.0bn, a test of whether private capital can revive a mature, asset-heavy food business whose growth has stalled.
The context
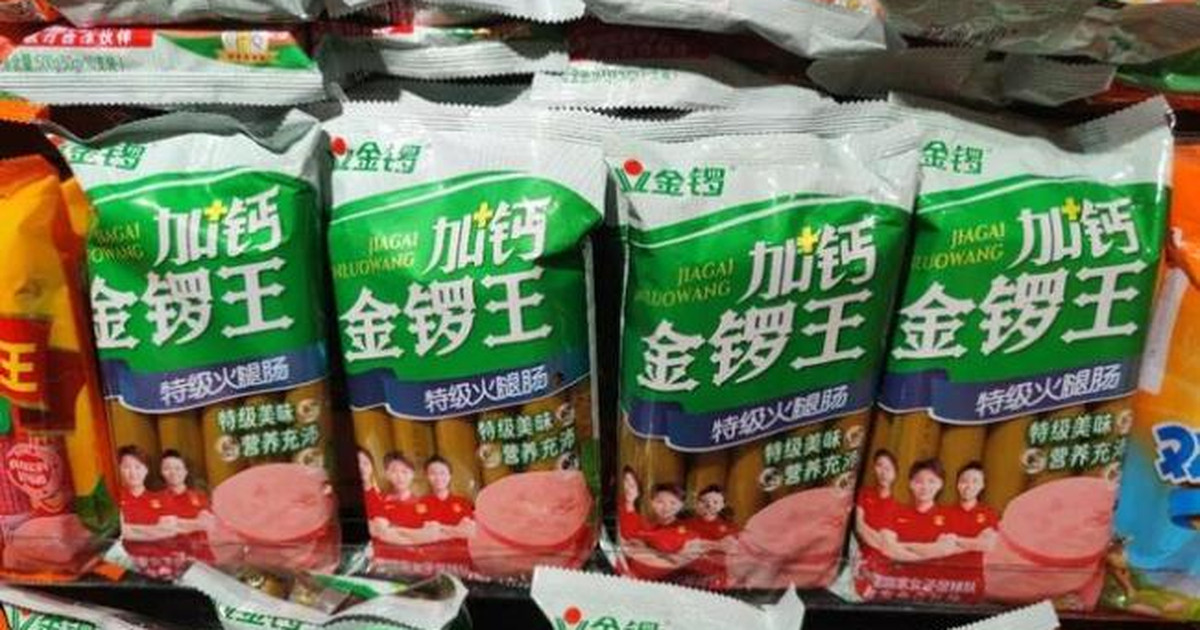
China's packaged-meat market is consolidated, slow-growing and sensitive to the price of pigs. Jinluo built its position on ham sausages sold through thousands of distributors, a model that rewards scale and punishes anyone who loses shelf space.
DCP's interest is a bet that operational discipline, not growth, is where the return sits. The firm's RT-Mart purchase followed the same logic: take a mature asset with a strong position, cut what can be cut and improve what can be measured.
The counter-argument
The bear case is that food is not retail. A supermarket can be fixed by logistics and pricing; a branded meat business depends on consumer habit, and ham sausage is a category with little premium left. Cost cuts may lift margins for a year or two, but they do not create a growth story an exit buyer will pay for.
There is also the price. At about US$2.0bn, DCP is paying a control premium for a business with RMB30.86bn of revenue but no disclosed profit. Leverage on a cyclical protein processor can turn a modest downturn into a covenant problem.
What happens next
Watch for confirmation and for the financing package. If the deal closes with modest leverage and DCP keeps the distribution team, the operational case is credible. If it is heavily debt-funded, the return depends on pig prices behaving.
From China.com, 11 November 2026.
Original source: China.com Finance · 11 Nov 2026